Buying · Montreal · mortgage 2026
What a 30-year rather than 25-year amortization changes in Montreal in 2026: the payment, the required income, the CMHC premium, the interest and the balance after 5 years, for the median house and condo.
For the median house in Montreal ($755,000, minimum down payment of $50,500), a 30-year amortization lowers the payment from $3,890 to $3,528 a month, or $362 less, and brings the required income down from $167,882 to $158,064. For the median condo ($476,100), it is $232 less a month ($2,497 versus $2,265) and a required income of $102,359 instead of $108,662. The price: about $101,786 more interest over the life of the house loan if the rate stayed at 4.09% and you never paid it down faster. Assumptions: Centris median price (January to September 2026) of single-family houses and condos; minimum down payment (5% up to $500,000, 10% on the portion above, 20% above $1.5M); CMHC premium added to the loan (2026 schedule, + 0.20 point over 30 years); insured 5-year fixed rate of 4.09% kept for the whole term (a scenario, not a forecast), compounded semi-annually; minimum income at the stress test rate (6.09%) with property taxes at 1% of the price and $1,200 a year of heating, 39% debt ratio. Source: Centris (Matrix) for prices, compiled October 31, 2026.
The short answer
For the median house in Montreal ($755,000, minimum down payment of $50,500), a 30-year amortization lowers the payment from $3,890 to $3,528 a month, or $362 less, and brings the required income down from $167,882 to $158,064. For the median condo ($476,100), it is $232 less a month ($2,497 versus $2,265) and a required income of $102,359 instead of $108,662. The price: about $101,786 more interest over the life of the house loan if the rate stayed at 4.09% and you never paid it down faster.
Payment and required income in Montreal, 25 or 30 years
| 2026 in Montreal | Median price | Minimum down payment | Payment over 25 years | Payment over 30 years | Savings per month | Required income, 25 years | Required income, 30 years |
|---|---|---|---|---|---|---|---|
| Median house | $755,000 | $50,500 | $3,890 | $3,528 | $362 | $167,882 | $158,064 |
| Median condo | $476,100 | $23,805 | $2,497 | $2,265 | $232 | $108,662 | $102,359 |
Centris (Matrix) median prices, January to September 2026; insured 5-year fixed rate of 4.09%.

What 30 years costs in Montreal
| In Montreal | CMHC premium, 25 years | CMHC premium, 30 years | Interest over 25 years | Interest over 30 years | Balance owed after 5 years, 25 years | Balance owed after 5 years, 30 years |
|---|---|---|---|---|---|---|
| Median house | $28,180 | $29,589 | $434,283 | $536,069 | $638,823 | $664,559 |
| Median condo | $18,092 | $18,996 | $278,813 | $344,160 | $410,130 | $426,652 |
What these numbers say in Montreal
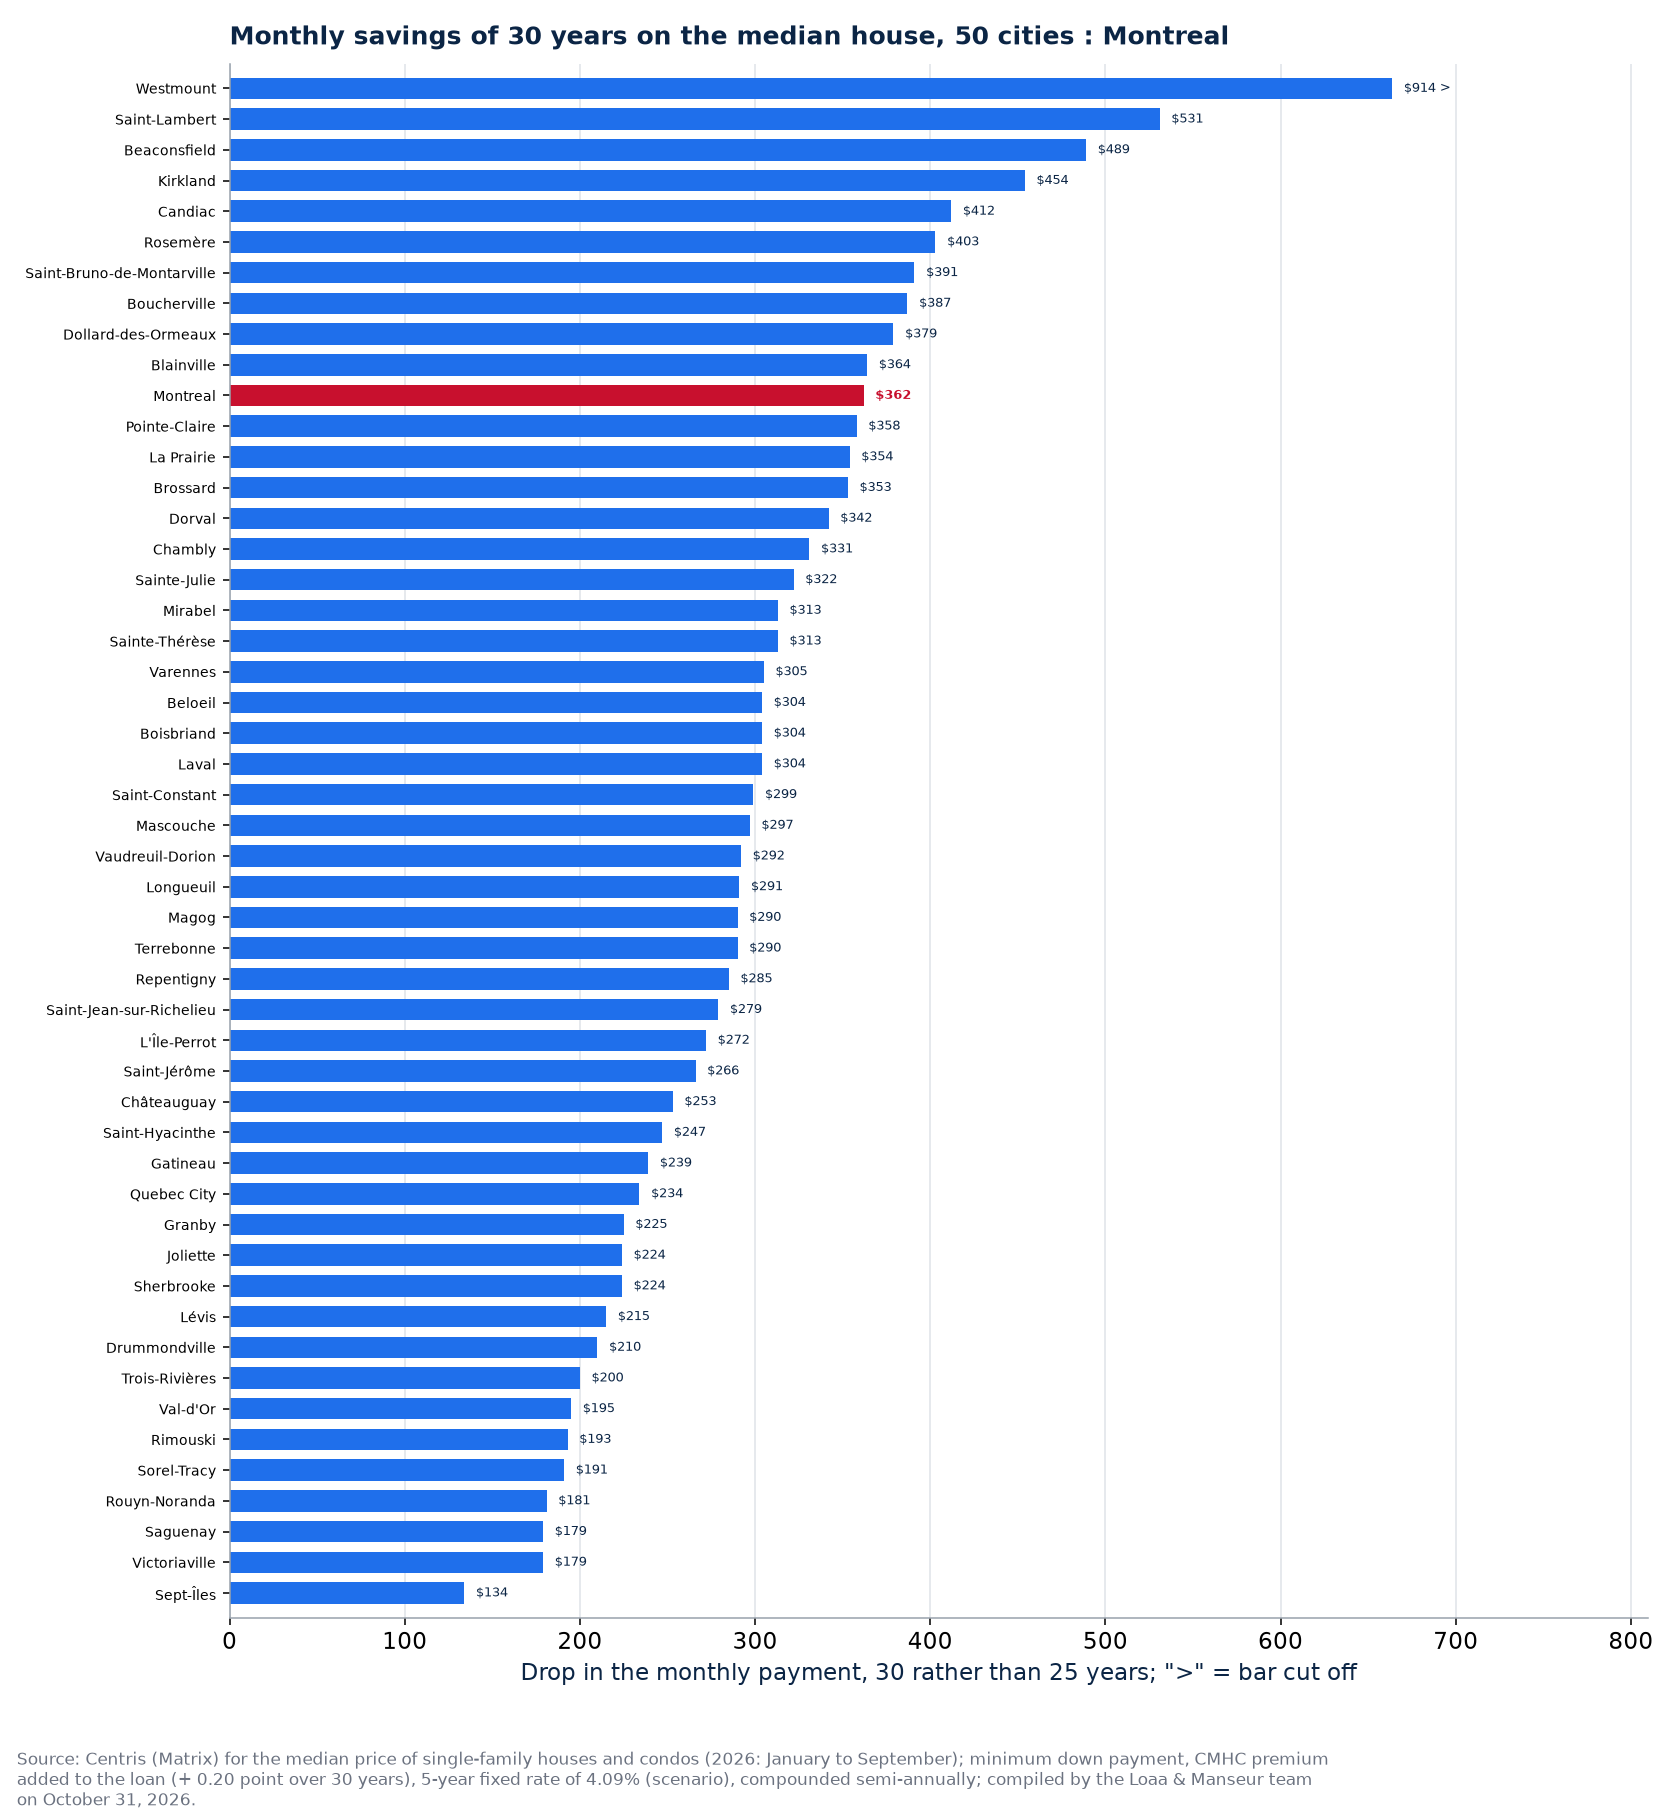
- Over 30 years, the median house in Montreal costs $4,344 less a year in payments, and the required income drops by $9,818 (5.8%): that is often what gets a first-time buyer's file approved.
- The 0.20-point surcharge costs $1,409 on the median house, added to the loan, plus $127 of Québec sales tax paid in cash at the notary.
- After 5 years (a first term), you owe $25,736 more with 30 years. At renewal, nothing stops you from going back to a shorter amortization if the budget allows.
- For the median condo in Montreal, 30 years frees up $232 a month and costs about $65,347 more interest over the life of the loan, at the same rate.
- Across the 50 cities tracked, 30 years lowers the median house payment by a median $294 a month and the median condo payment by $194 a month; the required income drops by about 5.8%.
Who qualifies for 30 years?
Since December 15, 2024, an insured mortgage (down payment under 20%) can be amortized over 30 years for all first-time buyers, whatever the property, and for any purchase of a newly built home. CMHC then adds 0.20 percentage point to the insurance premium (for example, 4.00% becomes 4.20%). With 20% down or more, the loan is not insured and a 30-year amortization depends on the lender.
What it changes for buying in Montreal
In Montreal, 30 years frees up more money each month than in most of the 50 cities tracked, because prices are higher. For a first-time buyer, it is often the difference between buying this year and renting longer. Now is the time: the choice is there, and the prepayment privileges most lenders allow let you shorten the term later. For the cash to plan for: the cash for a house in Montreal, the cash for a condo in Montreal.
How to read these numbers
Assumptions: Centris median price (January to September 2026) of single-family houses and condos; minimum down payment (5% up to $500,000, 10% on the portion above, 20% above $1.5M); CMHC premium added to the loan (2026 schedule, + 0.20 point over 30 years); insured 5-year fixed rate of 4.09% kept for the whole term (a scenario, not a forecast), compounded semi-annually; minimum income at the stress test rate (6.09%) with property taxes at 1% of the price and $1,200 a year of heating, 39% debt ratio. Total interest is a constant-rate scenario with no prepayment: in practice, the rate changes at every renewal and every extra payment narrows the gap. The welcome tax, notary and other cash costs are the same in both cases.
Frequently asked questions
Who can take a 30-year amortization in Montreal?
Since December 15, 2024, an insured mortgage (down payment under 20%) can be amortized over 30 years for all first-time buyers, whatever the property, and for any purchase of a newly built home. CMHC then adds 0.20 percentage point to the insurance premium (for example, 4.00% becomes 4.20%). With 20% down or more, the loan is not insured and a 30-year amortization depends on the lender.
How much more does 30 years cost?
For the median house in Montreal, about $101,786 more interest over the life of the loan and a $1,409 surcharge, at a constant 4.09% rate with no prepayment; for the median condo, about $65,347.
Can you shorten the amortization later?
Yes. Most mortgages allow prepayments every year, and renewal (often after 5 years) lets you pick a shorter amortization. Thirty years gives room at the start; nothing forces you to keep it to the end. See also mortgage renewal in 2026-2027 and CMHC mortgage insurance in 2026.
Sources: Centris (Matrix), Statistics module, median sale price of single-family houses and condos for the municipality of Montreal (query of September 16, 2026); Department of Finance Canada (30-year amortization for first-time buyers and new builds, in force December 15, 2024); CMHC premium schedule; compiled by the Loaa & Manseur team, aggregates only. The hub 25 or 30-year amortization in 50 cities compares the 50 cities.
Our proof, not our promises
The Loaa & Manseur team, led by Lotfi Manseur and Loaa Al Daow, is the number 1 team at RE/MAX Platine in 2024 and 2025, 6th RE/MAX team in Quebec, 15th in Canada and in the global top 50 of large residential teams according to the official RE/MAX ranking, computed on actual transactions. Its Google profile counts more than 220 reviews with a 4.9 rating. Its offices are at 55 avenue de l'Équinoxe in Brossard, one bridge from the island, and every broker's licence can be checked in the OACIQ public register. Three things to verify yourself before calling us, and to demand of any other broker.
Also available in French: version française de ce guide.
Published September 7, 2026 by the Loaa & Manseur team, the number 1 team at RE/MAX Platine in 2024 and 2025, 6th RE/MAX team in Quebec, 15th in Canada and in the global top 50 according to the official RE/MAX ranking. Tell us about your project.