Salary to buy · Dorval · 2016 vs 2026
The gross income it takes to buy the median house in Dorval, computed for every year from 2016 to 2026 with the Centris price and the year's contracted rate: how much more than in 2016, and the price's and the rate's share of the increase. Labelled assumptions, nothing estimated on prices.
To buy the median house in Dorval, a household needed a gross income of about $58,238 in 2016 (price of $324,000, rate of 2.67%) and needs about $140,091 in 2026 (price of $712,500 over January to September 2026, rate of 4.14%): $81,853 more, +141%, for a price up 120%. The monthly housing cost (mortgage at 20% down over 25 years, taxes at 1% of the price, heating) went from $1,553 to $3,736; the mortgage is 81% of it. Of the $81,853 increase, the price explains $65,353 and the rate $16,500 (20%). It is one of the highest required salaries among the 50 cities tracked (median $120,462 in 2026, $47,644 in 2016). Assumptions: 20% down payment, 25-year amortization, the year's average contracted rate (2.67% in 2016, 2.13% in 2021, 4.14% in 2026), municipal and school taxes estimated at 1% of the price per year, heating and electricity at $1,200 per year, 32% gross debt service ratio. Source: Centris (Matrix) for prices, compiled October 13, 2026.
The short answer
To buy the median house in Dorval, a household needed a gross income of about $58,238 in 2016 (price of $324,000, rate of 2.67%) and needs about $140,091 in 2026 (price of $712,500 over January to September 2026, rate of 4.14%): $81,853 more, +141%, for a price up 120%. The monthly housing cost (mortgage at 20% down over 25 years, taxes at 1% of the price, heating) went from $1,553 to $3,736; the mortgage is 81% of it. Of the $81,853 increase, the price explains $65,353 and the rate $16,500 (20%). It is one of the highest required salaries among the 50 cities tracked (median $120,462 in 2026, $47,644 in 2016).
The salary required for the median house in Dorval, 2016 to 2026

| Year | Median house | 5-year contracted rate | Monthly mortgage payment | Monthly housing cost | Gross salary required |
|---|---|---|---|---|---|
| 2016 | $324,000 | 2.67% | $1,183 | $1,553 | $58,238 |
| 2017 | $390,000 | 2.87% | $1,456 | $1,881 | $70,538 |
| 2018 | $424,000 | 3.49% | $1,692 | $2,145 | $80,450 |
| 2019 | $448,000 | 3.17% | $1,728 | $2,201 | $82,550 |
| 2020 | $540,000 | 2.44% | $1,922 | $2,472 | $92,700 |
| 2021 | $612,500 | 2.13% | $2,106 | $2,716 | $101,866 |
| 2022 | $583,500 | 3.90% | $2,430 | $3,016 | $113,109 |
| 2023 | $629,444 | 5.26% | $3,004 | $3,628 | $136,069 |
| 2024 | $661,500 | 4.96% | $3,066 | $3,717 | $139,397 |
| 2025 | $716,250 | 4.20% | $3,077 | $3,774 | $141,519 |
| 2026 | $712,500 | 4.14% | $3,042 | $3,736 | $140,091 |
Median price of single-family houses sold on Centris (Matrix) by year (2026: January to September 2026); average 5-year contracted rate (Bank of Canada, Statistics Canada 10-10-0006); payment at 20% down over 25 years; housing cost = payment + taxes estimated at 1% of the price + heating $1,200 per year; required salary = annual cost ÷ 32%.
What the comparison says in Dorval
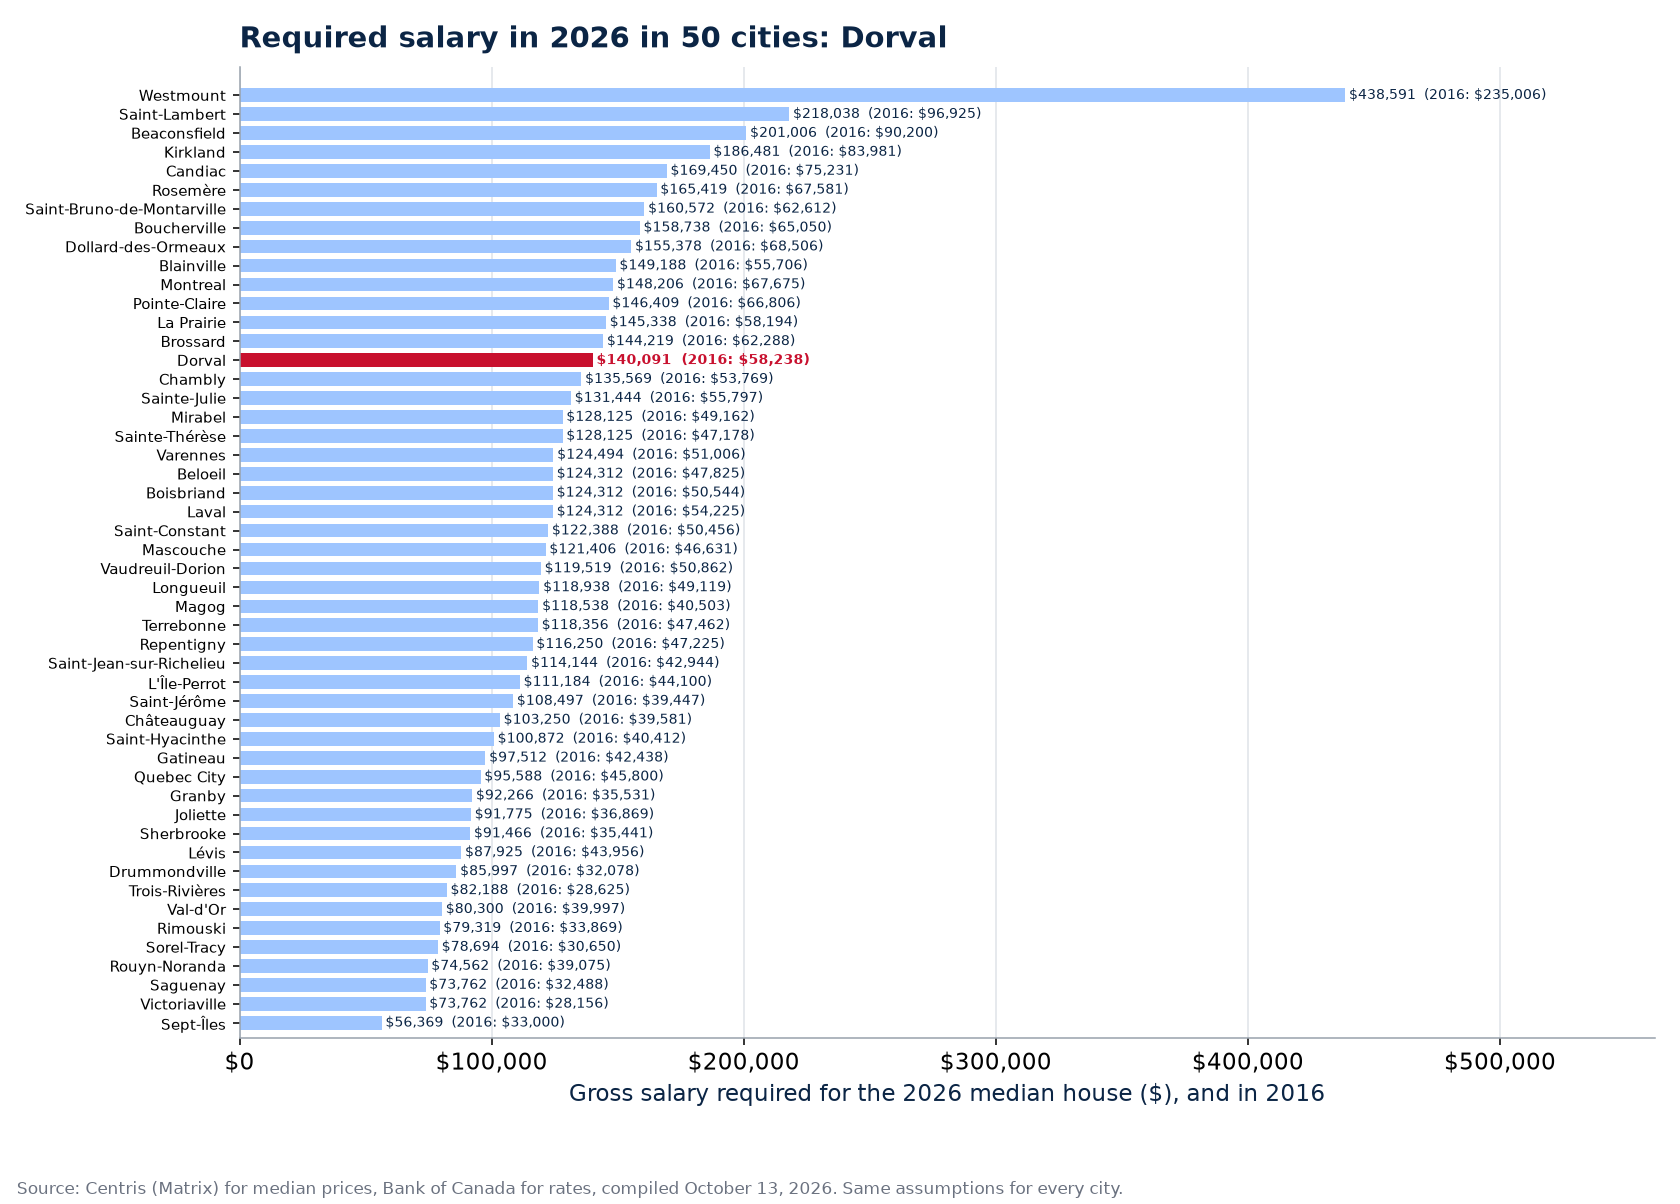
- The price rose 120% and the required salary 141% in Dorval: the rate did the rest, 2.67% in 2016 against 4.14% in 2026. At the 2016 rate, the 2026 house would require $123,591 of salary instead of $140,091.
- The decade's lowest rate, in 2021: $101,866 of salary required for a house at $612,500 at a 2.13% rate. From 2021 to 2026, the required salary rose 38% in Dorval, the price 16%.
- One more point of rate in 2026 would add $11,962 to the required salary in Dorval; one point less would remove about as much, 9% of the required salary, the equivalent of a price increase of the same order.
- The price ÷ required salary ratio went from 5.6 to 5.1 in Dorval: it takes $19,662 of income per $100,000 of price in 2026.
- Across the 50 cities tracked, the salary required for the median house went from $47,644 to $120,462 in median (+144%, price +124%); it doubled in 47 cities, exceeds $100,000 in 35 cities (against 1 in 2016) and $150,000 in 9. In 2016, 38 cities made do with $60,000; in 2026, 1.
What it changes for buying or selling in Dorval
In Dorval, the required salary rose +141% in ten years, in line with the 50 cities tracked (median +144%). At $140,091 of gross income with 20% down, the median house calls for a two-income household or a buyer who is selling; with the minimum down payment, the insurance premium and the lender's qualifying rate, the bar rises further: that is the calculation in what salary to buy a house in Dorval. For a seller, the required income says who your buyer is, and therefore how they compare. The payment alone, year by year, is in mortgage payment on the median house in Dorval; the down payment in down payment to buy in Dorval.
How to read these figures
The required salary is the household's gross annual income such that the housing cost (mortgage payment, municipal and school taxes, heating) is 32% of income, the gross debt service (GDS) ratio lenders use. Assumptions: 20% down payment, 25-year amortization, the year's average contracted rate (2.67% in 2016, 2.13% in 2021, 4.14% in 2026), municipal and school taxes estimated at 1% of the price per year, heating and electricity at $1,200 per year, 32% gross debt service ratio. Other debts (car, cards) reduce capacity accordingly; the lender's qualifying rate (contract rate plus 2 points) is not applied here, which makes the calculation more favourable than actual qualification.
Frequently asked questions
What salary does it take to buy the median house in Dorval in 2026?
About $140,091 of gross household income for the median house at $712,500 (January to September 2026), with 20% down, 25-year amortization, the 4.14% contracted rate, taxes at 1% of the price and $1,200 of heating, at a 32% GDS ratio. With the minimum down payment and the qualifying rate, more is needed.
And in 2016, how much did it take in Dorval?
In 2016, the median house in Dorval cost $324,000 and the rate was 2.67%: $58,238 of income was enough. In 2026, $140,091: +141%. The price explains $65,353 of the increase and the rate $16,500.
Was it the price or the rate that pushed the required salary up in Dorval?
The price first: at the 2016 rate, the 2026 house would already require $123,591, +112% against 2016. The rate adds $16,500, 20% of the increase in Dorval. Across the 50 cities, the rate's share is 20% in median.
Sources: Centris (Matrix), Statistics module, September 16, 2026 query for the municipality of Dorval, median sale price of single-family houses by year; Bank of Canada and Statistics Canada (table 10-10-0006) for contracted rates; tax and heating assumptions labelled; compiled by the Loaa & Manseur team, aggregates only. The salary to buy the median house in 50 cities hub compares the 50 cities.
Our proof, not our promises
The Loaa & Manseur team, led by Lotfi Manseur and Loaa Al Daow, is the number 1 team at RE/MAX Platine in 2024 and 2025, 6th RE/MAX team in Quebec, 15th in Canada and in the global top 50 of large residential teams according to the official RE/MAX ranking, computed on actual transactions. Its Google profile counts more than 220 reviews with a 4.9 rating. Its offices are at 55 avenue de l'Équinoxe in Brossard, one bridge from the island, and every broker's licence can be checked in the OACIQ public register. Three things to verify yourself before calling us, and to demand of any other broker.
Also available in French: version française de ce guide.
Published September 7, 2026 by the Loaa & Manseur team, the number 1 team at RE/MAX Platine in 2024 and 2025, 6th RE/MAX team in Quebec, 15th in Canada and in the global top 50 according to the official RE/MAX ranking. Tell us about your project.