Buying · Saint-Bruno-de-Montarville · down payment 2026
Buy now with the minimum down payment or wait for 20% in Saint-Bruno-de-Montarville: the real cost of the CMHC premium, the saving time, rent and prices during the wait, median house and condo.
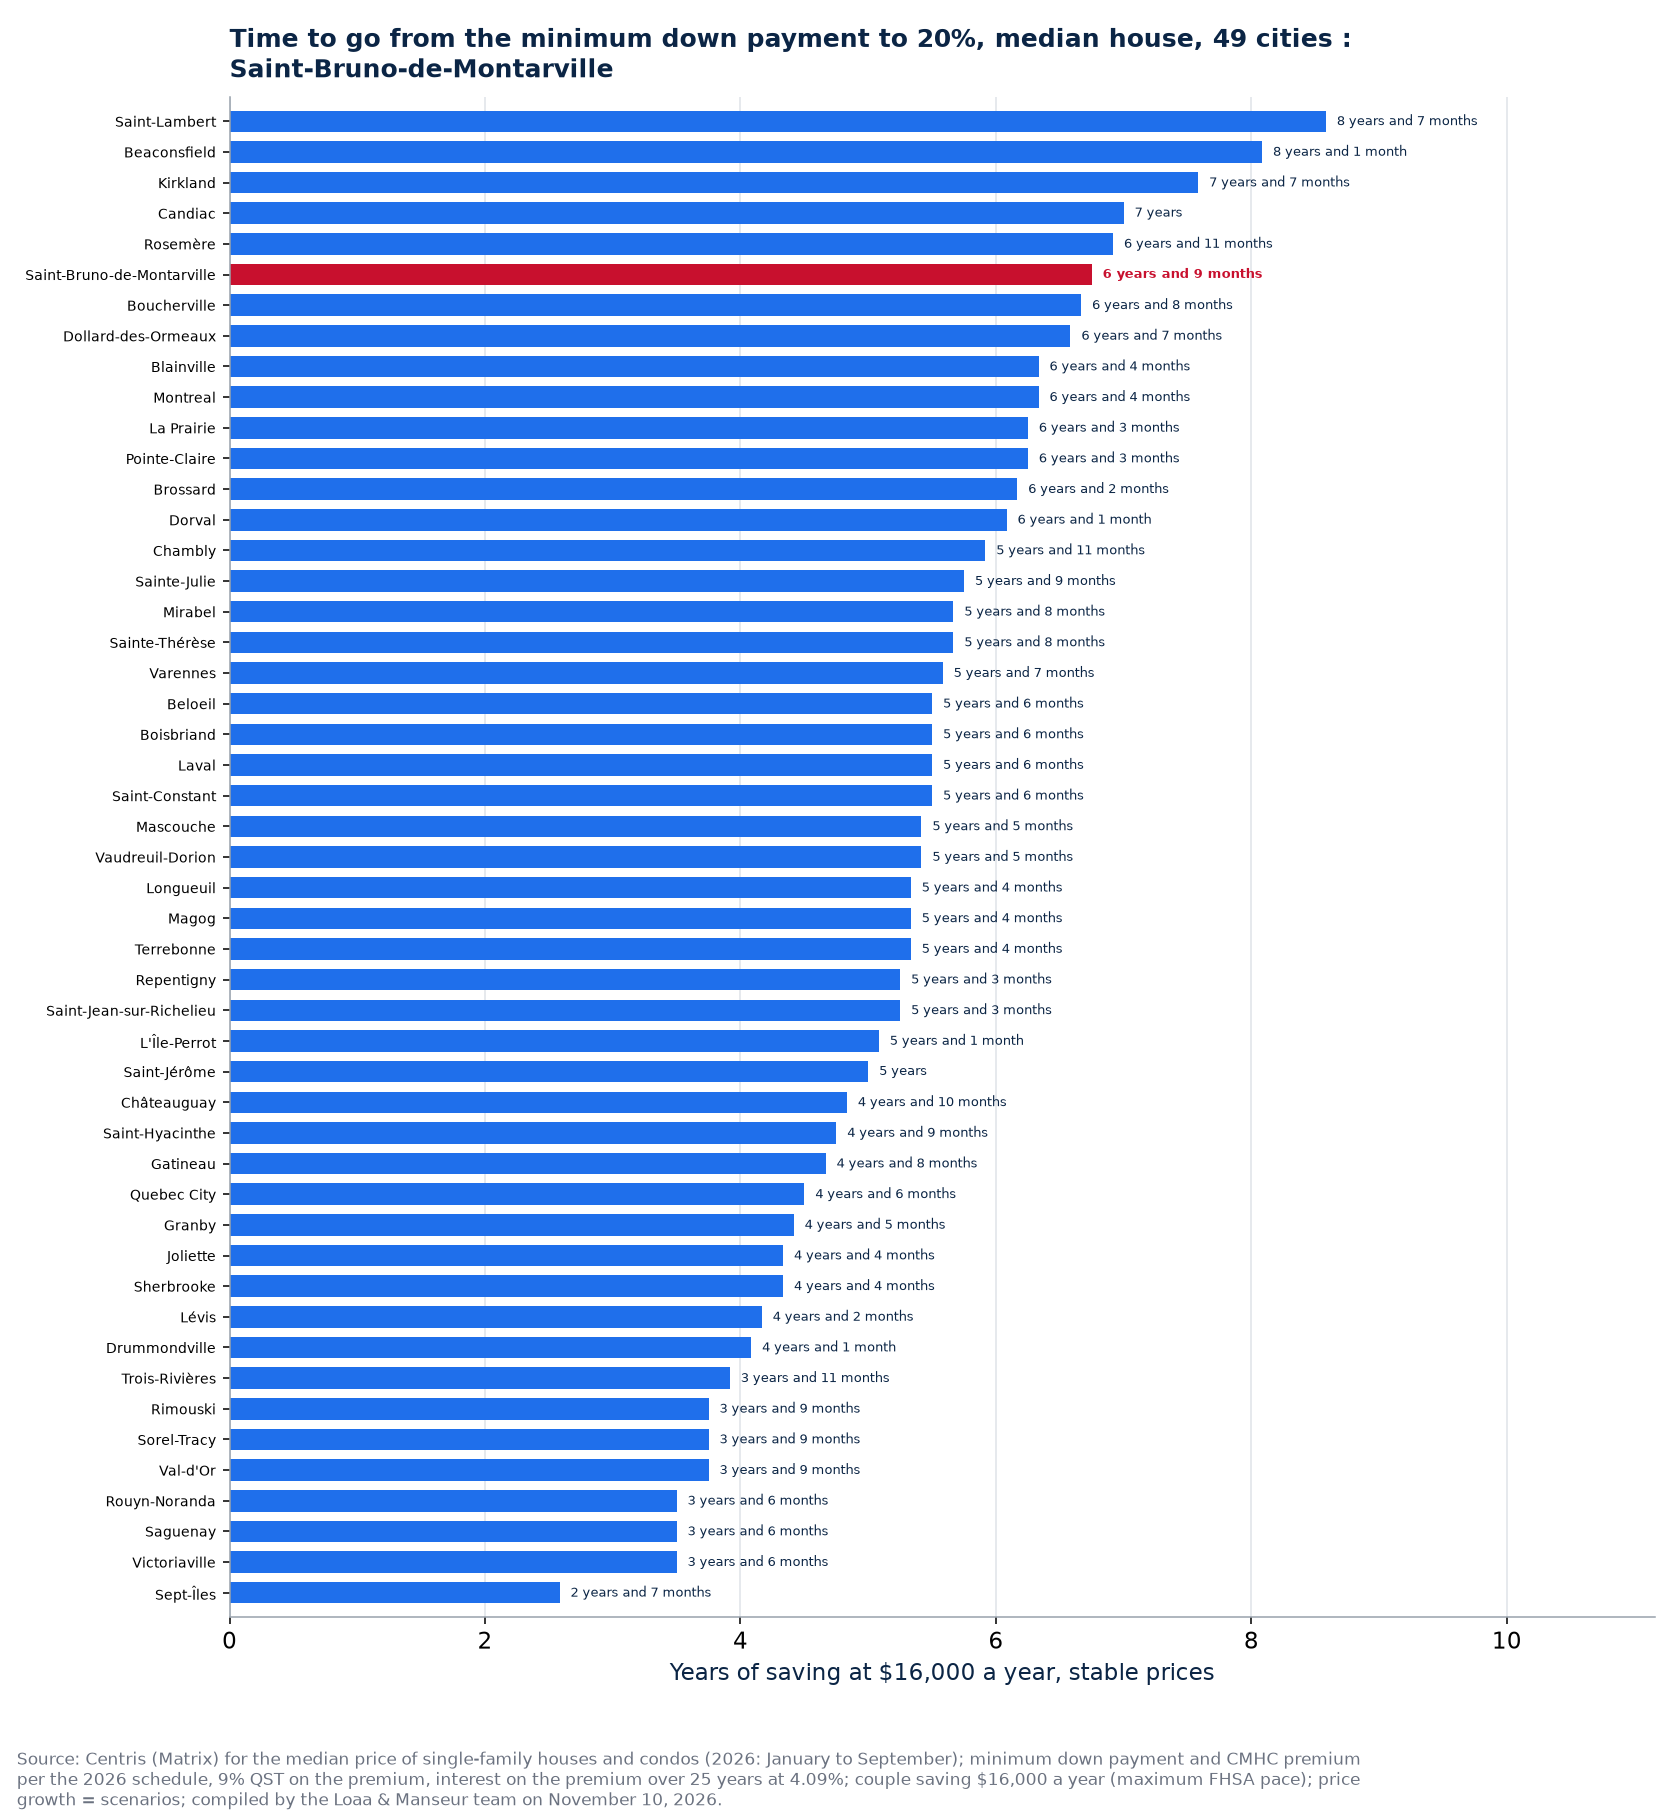
For the median house in Saint-Bruno-de-Montarville ($819,500), the minimum down payment is $56,950 and 20% is $163,900, or $106,950 more to save. At $16,000 a year (a couple maxing out the FHSA), that is 6 years and 9 months of waiting, at stable prices. Buying now costs the CMHC premium ($30,502, added to the loan), the Québec sales tax on the premium ($2,745) and about $18,079 of interest on the premium over 25 years: $51,326 in all. Prices only need to rise 0.91% a year during the wait for waiting to cost more than the premium, without even counting rent. Assumptions: Centris median price (January to September 2026) of single-family houses and condos; minimum down payment and CMHC premium per the 2026 schedule; interest on the premium = payment gap over 25 years at a 4.09% fixed rate; a couple saving at the maximum FHSA pace, $16,000 a year ($8,000 each), starting from the minimum down payment already saved; price growth = change in the city's Centris median price from 2025 to 2026, used as a scenario, not a forecast. Source: Centris (Matrix) for prices, compiled on November 10, 2026.
The short answer
For the median house in Saint-Bruno-de-Montarville ($819,500), the minimum down payment is $56,950 and 20% is $163,900, or $106,950 more to save. At $16,000 a year (a couple maxing out the FHSA), that is 6 years and 9 months of waiting, at stable prices. Buying now costs the CMHC premium ($30,502, added to the loan), the Québec sales tax on the premium ($2,745) and about $18,079 of interest on the premium over 25 years: $51,326 in all. Prices only need to rise 0.91% a year during the wait for waiting to cost more than the premium, without even counting rent.
Buying now in Saint-Bruno-de-Montarville: what the premium costs
| 2026 in Saint-Bruno-de-Montarville | Median price | Minimum down payment | 20% down payment | Wait to reach 20% | CMHC premium | QST on the premium | Interest on the premium (25 years) | Total cost of the premium |
|---|---|---|---|---|---|---|---|---|
| Median house | $819,500 | $56,950 | $163,900 | 6 years and 9 months | $30,502 | $2,745 | $18,079 | $51,326 |
| Median condo | $494,000 | $24,700 | $98,800 | 4 years and 8 months | $18,772 | $1,689 | $11,127 | $31,588 |
Centris (Matrix) median prices, January to September 2026; 2026 premium schedule; insured 5-year fixed rate of 4.09%, 25 years.

Waiting for 20% in Saint-Bruno-de-Montarville: what it costs
| In Saint-Bruno-de-Montarville, during the wait | Price 2025 to 2026 | Price increase if that pace continues | Increase per 1% a year | Yearly growth that makes waiting cost more than the premium | Rent paid during the wait |
|---|---|---|---|---|---|
| Median house | -1.3% | $-67,484 | $56,932 | 0.91% | n/a |
| Median condo | +7.4% | $195,048 | $23,480 | 1.34% | n/a |
What these numbers say in Saint-Bruno-de-Montarville
- The premium adds about $162 a month to the payment on the median house in Saint-Bruno-de-Montarville. That is the real monthly cost of not having 20%.
- The median house price in Saint-Bruno-de-Montarville fell 1.3% from 2025 to 2026. Even with stable or slightly lower prices, waiting is paid in rent and years.
- For the median condo ($494,000), the wait is 4 years and 8 months and the premium costs $31,588 all in; the threshold is a 1.34% yearly price rise.
- In the 49 cities where the median house is insurable, it takes a median 5 years and 5 months to reach 20% on the median house, and the premium costs $38,332 all in. A price rise of about 1.15% a year is enough for waiting to cost more.
Down payment rules
With less than 20% down, the mortgage must be insured (CMHC or another insurer): the premium, from 2.80% to 4.00% of the loan depending on the down payment, is added to the loan, and the 9% Québec sales tax on the premium is paid in cash at the notary. The minimum down payment is 5% up to $500,000 and 10% on the portion between $500,000 and $1.5M; from $1.5M, 20% is required.
What it changes for buying in Saint-Bruno-de-Montarville
In Saint-Bruno-de-Montarville, the wait to reach 20% is among the longest of the 50 cities tracked: every year of waiting is another year of rent and prices that can rise. For most buyers, buying with the minimum down payment and planning prepayments costs less than waiting. Now is the time to buy, with a plan. For the cash to plan for: the cash for a house in Saint-Bruno-de-Montarville, the cash for a condo in Saint-Bruno-de-Montarville.
How to read these numbers
Assumptions: Centris median price (January to September 2026) of single-family houses and condos; minimum down payment and CMHC premium per the 2026 schedule; interest on the premium = payment gap over 25 years at a 4.09% fixed rate; a couple saving at the maximum FHSA pace, $16,000 a year ($8,000 each), starting from the minimum down payment already saved; price growth = change in the city's Centris median price from 2025 to 2026, used as a scenario, not a forecast. The yearly growth threshold counts neither rent nor the savings that could be used elsewhere: it favours waiting, and waiting is still often more expensive. The welcome tax and notary fees are the same in both cases.
Frequently asked questions
Do you need 20% down to buy in Saint-Bruno-de-Montarville?
No. With less than 20% down, the mortgage must be insured (CMHC or another insurer): the premium, from 2.80% to 4.00% of the loan depending on the down payment, is added to the loan, and the 9% Québec sales tax on the premium is paid in cash at the notary. The minimum down payment is 5% up to $500,000 and 10% on the portion between $500,000 and $1.5M; from $1.5M, 20% is required.
How much does the CMHC premium cost in Saint-Bruno-de-Montarville?
For the median house in Saint-Bruno-de-Montarville, about $51,326: the $30,502 premium added to the loan, $2,745 of QST paid in cash and about $18,079 of interest on the premium over 25 years, at 4.09%.
Can you get rid of the premium later?
The premium is paid once, at purchase. It is not refunded, but prepayments allowed by your contract reduce the interest you pay on it. See also biweekly mortgage payments in Saint-Bruno-de-Montarville and 25 or 30-year amortization in Saint-Bruno-de-Montarville.
Sources: Centris (Matrix), Statistics module, median sale price of single-family houses and condos for the municipality of Saint-Bruno-de-Montarville (2025 and January to September 2026); CMHC mortgage loan insurance premium schedule; Government of Canada minimum down payment rules ($1.5M insurable limit since December 15, 2024); FHSA annual limit (Canada Revenue Agency); compiled by the Loaa & Manseur team, aggregates only. The hub waiting for 20% down in 50 cities compares the 50 cities.
Our proof, not our promises
The Loaa & Manseur team, led by Lotfi Manseur and Loaa Al Daow, is the number 1 team at RE/MAX Platine in 2024 and 2025, 6th RE/MAX team in Quebec, 15th in Canada and in the global top 50 of large residential teams according to the official RE/MAX ranking, computed on actual transactions. Its Google profile counts more than 220 reviews with a 4.9 rating. Its offices are at 55 avenue de l'Équinoxe in Brossard, one bridge from the island, and every broker's licence can be checked in the OACIQ public register. Three things to verify yourself before calling us, and to demand of any other broker.
Also available in French: version française de ce guide.
Published September 7, 2026 by the Loaa & Manseur team, the number 1 team at RE/MAX Platine in 2024 and 2025, 6th RE/MAX team in Quebec, 15th in Canada and in the global top 50 according to the official RE/MAX ranking. Tell us about your project.