Rates · 52 cities · October 28, 2026
One page per city: the payment before and after the increase, the down payment, the income to qualify and the state of the local market.
After the policy rate increase to 2.5% on October 28, 2026, the variable payment on the median house rises by $82 per month at the median of the 52 cities, and the minimum income to qualify by about $2,750. Loaa & Manseur team calculations, Centris prices for Q3 2026.
The short answer
On October 28, 2026, the Bank of Canada raised its policy rate from 2.25% to 2.5%. For the median house of Q3 2026 bought with the minimum down payment and a variable-rate mortgage, the payment rises by $82 per month at the median of the 52 cities, and the minimum income to qualify by about $2,750. The pricier the house, the bigger the gap: from +$41 in Sept-Îles to +$277 in Westmount. On a fixed rate, the announcement changes nothing for now. For the decision itself, see the policy rate increase explained.
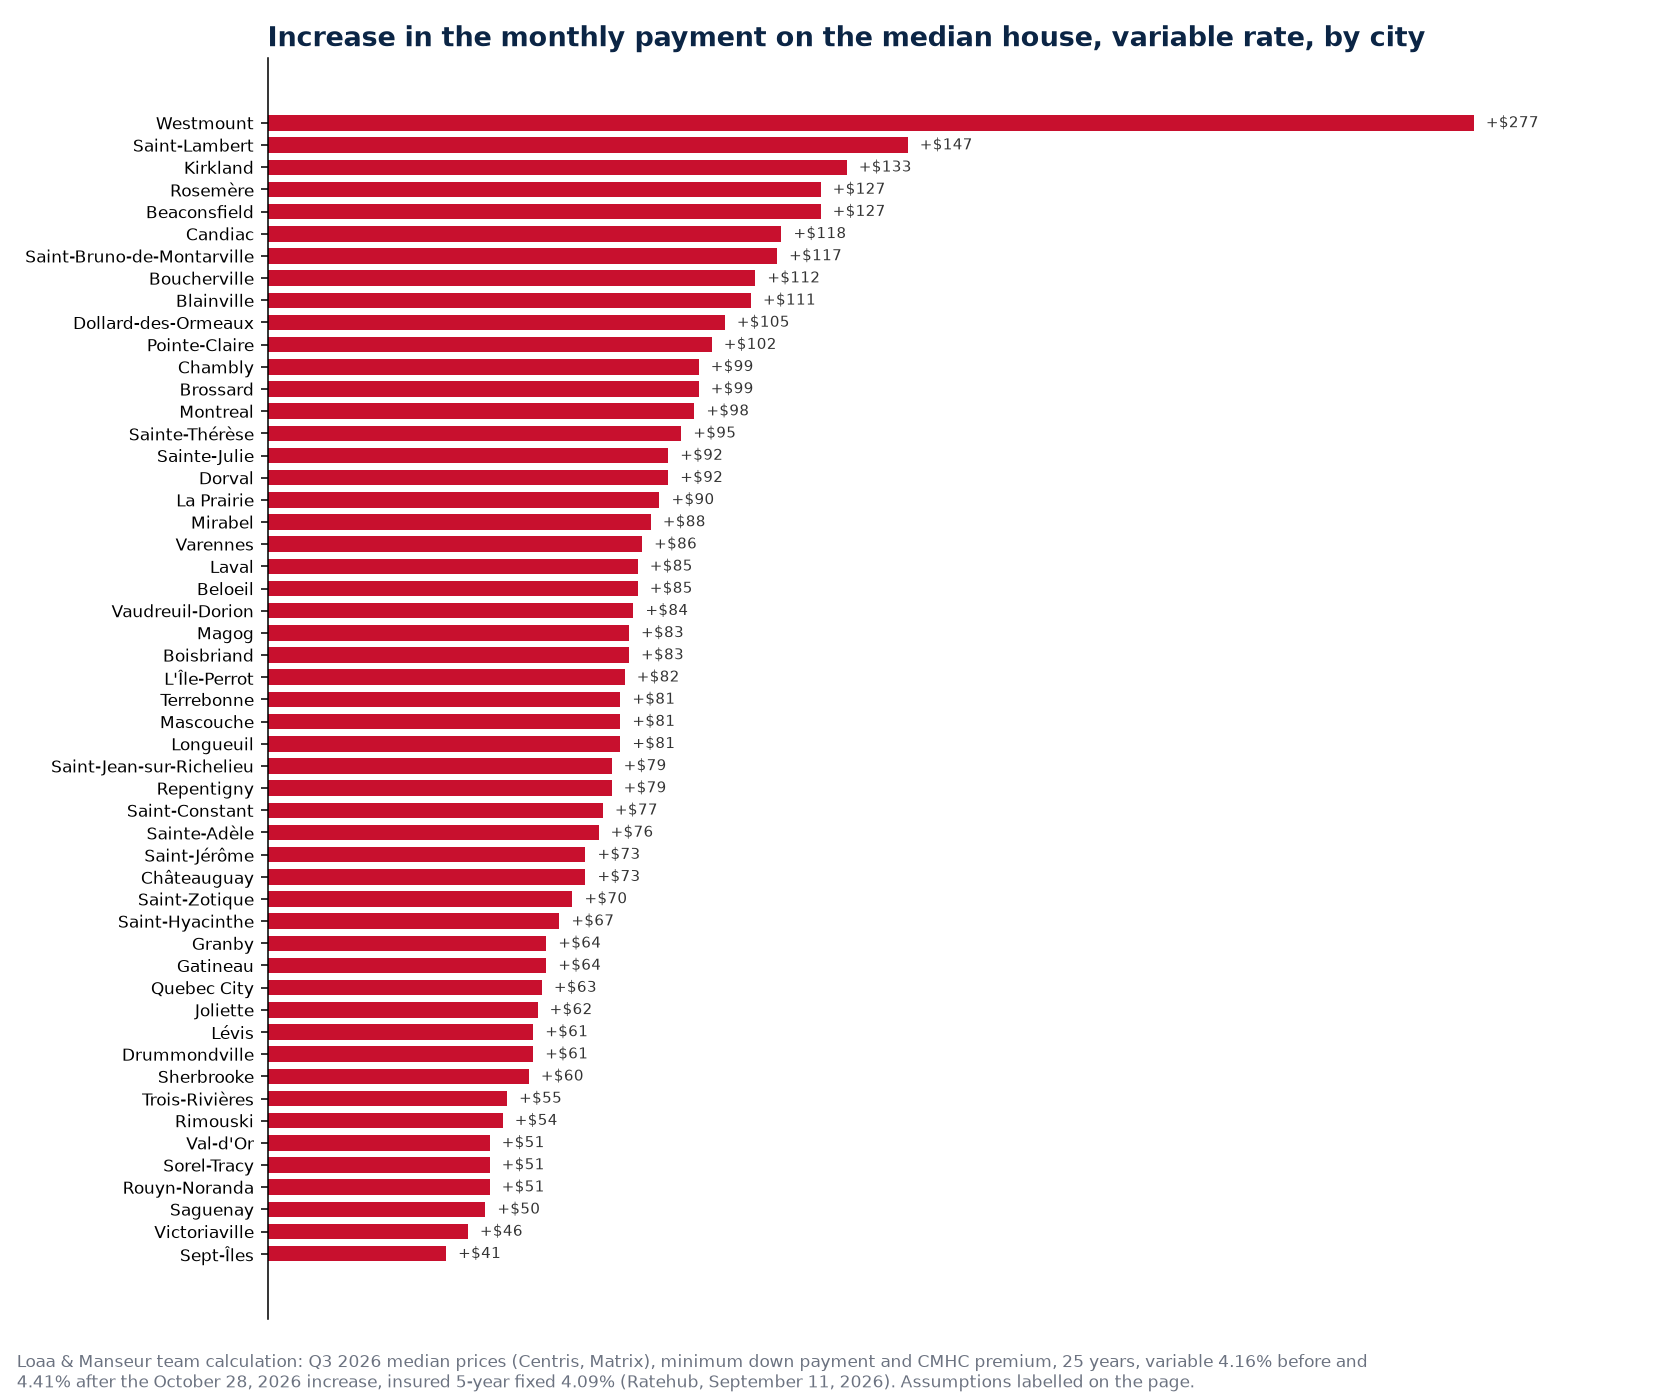
The 52 cities
| City | Median house Q3 2026 | Variable payment after | Increase per month | Minimum income (variable) | 5-year fixed payment |
|---|---|---|---|---|---|
| Westmount | $2,525,000 | $11,079 | +$277 | $480,757 | $10,724 |
| Saint-Lambert | $1,120,000 | $5,892 | +$147 | $251,411 | $5,704 |
| Kirkland | $1,005,000 | $5,302 | +$133 | $226,459 | $5,132 |
| Beaconsfield | $960,000 | $5,071 | +$127 | $216,694 | $4,909 |
| Rosemère | $958,000 | $5,061 | +$127 | $216,260 | $4,899 |
| Candiac | $889,000 | $4,707 | +$118 | $201,289 | $4,556 |
| Saint-Bruno-de-Montarville | $882,500 | $4,673 | +$117 | $199,878 | $4,523 |
| Boucherville | $838,750 | $4,449 | +$112 | $190,385 | $4,306 |
| Blainville | $832,000 | $4,414 | +$111 | $188,921 | $4,273 |
| Dollard-des-Ormeaux | $791,000 | $4,203 | +$105 | $180,024 | $4,069 |
| Pointe-Claire | $759,500 | $4,042 | +$102 | $173,190 | $3,912 |
| Brossard | $739,500 | $3,939 | +$99 | $168,850 | $3,813 |
| Chambly | $740,000 | $3,942 | +$99 | $168,958 | $3,815 |
| Montreal | $735,000 | $3,916 | +$98 | $167,874 | $3,790 |
| Sainte-Thérèse | $710,000 | $3,788 | +$95 | $162,449 | $3,666 |
| Dorval | $694,000 | $3,705 | +$92 | $158,977 | $3,587 |
| Sainte-Julie | $690,000 | $3,685 | +$92 | $158,109 | $3,567 |
| La Prairie | $673,500 | $3,600 | +$90 | $154,529 | $3,485 |
| Mirabel | $650,000 | $3,480 | +$88 | $149,430 | $3,368 |
| Varennes | $643,750 | $3,447 | +$86 | $148,074 | $3,337 |
| Beloeil | $637,500 | $3,415 | +$85 | $146,718 | $3,306 |
| Laval | $630,000 | $3,377 | +$85 | $145,090 | $3,269 |
| Vaudreuil-Dorion | $620,250 | $3,327 | +$84 | $142,975 | $3,220 |
| Boisbriand | $622,500 | $3,338 | +$83 | $143,463 | $3,231 |
| Magog | $614,000 | $3,295 | +$83 | $141,619 | $3,189 |
| L'Île-Perrot | $611,000 | $3,279 | +$82 | $140,968 | $3,174 |
| Longueuil | $598,000 | $3,213 | +$81 | $138,147 | $3,110 |
| Mascouche | $600,000 | $3,223 | +$81 | $138,581 | $3,120 |
| Terrebonne | $604,000 | $3,243 | +$81 | $139,449 | $3,140 |
| Repentigny | $589,500 | $3,169 | +$79 | $136,303 | $3,067 |
| Saint-Jean-sur-Richelieu | $585,000 | $3,146 | +$79 | $135,326 | $3,045 |
| Saint-Constant | $574,000 | $3,089 | +$77 | $132,939 | $2,990 |
| Sainte-Adèle | $560,000 | $3,018 | +$76 | $129,902 | $2,921 |
| Châteauguay | $540,000 | $2,915 | +$73 | $125,562 | $2,821 |
| Saint-Jérôme | $540,000 | $2,915 | +$73 | $125,562 | $2,821 |
| Saint-Zotique | $519,000 | $2,807 | +$70 | $121,005 | $2,717 |
| Saint-Hyacinthe | $500,000 | $2,709 | +$67 | $116,883 | $2,623 |
| Gatineau | $469,290 | $2,543 | +$64 | $109,893 | $2,462 |
| Granby | $471,500 | $2,555 | +$64 | $110,396 | $2,473 |
| Quebec City | $460,000 | $2,493 | +$63 | $107,778 | $2,413 |
| Joliette | $458,000 | $2,482 | +$62 | $107,323 | $2,402 |
| Drummondville | $449,300 | $2,435 | +$61 | $105,343 | $2,357 |
| Lévis | $449,000 | $2,433 | +$61 | $105,275 | $2,355 |
| Sherbrooke | $447,747 | $2,426 | +$60 | $104,989 | $2,349 |
| Trois-Rivières | $400,000 | $2,168 | +$55 | $94,122 | $2,098 |
| Rimouski | $395,250 | $2,142 | +$54 | $93,041 | $2,073 |
| Rouyn-Noranda | $380,000 | $2,059 | +$51 | $89,569 | $1,993 |
| Sorel-Tracy | $372,750 | $2,020 | +$51 | $87,919 | $1,955 |
| Val-d'Or | $375,000 | $2,032 | +$51 | $88,431 | $1,967 |
| Saguenay | $365,500 | $1,981 | +$50 | $86,269 | $1,917 |
| Victoriaville | $342,400 | $1,855 | +$46 | $81,011 | $1,796 |
| Sept-Îles | $302,500 | $1,639 | +$41 | $71,929 | $1,587 |
What the table says
The market did not wait for the increase to slow down: in our quarterly study, January-to-September sales are down in 35 of 52 cities and houses sell more slowly in 35. For a pre-approved buyer, that means more choice and more room to negotiate. With the increase, the insured 5-year fixed (4.09%) is now below the variable (4.41%) in our assumptions, and easier to qualify for.
Method
Assumptions: a 4.16% variable rate before the increase (average surveyed in September 2026) and 4.41% after, the same quarter point as the policy rate; insured 5-year fixed at 4.09% (best rate in the Ratehub survey of September 11, 2026), unchanged by the announcement; 25-year amortization, interest compounded semi-annually; minimum down payment and CMHC premium under federal rules; minimum income = payment at the qualifying rate (the higher of 5.25% or the rate plus 2 points) plus municipal taxes estimated at 1% of the price and $1,200 of heating per year, divided by 39%, the gross debt service limit for insured mortgages. Your lender assesses your file its own way. Prices: median single-family house and condo of Q3 2026, Centris (Matrix), compiled on October 28, 2026.
Frequently asked questions
My city is not listed?
A broker on our team redoes the same calculation for any area and any price.
Also available in French: version française de ce guide.
Published September 7, 2026 by the Loaa & Manseur team, the number 1 team at RE/MAX Platine in 2024 and 2025, 6th RE/MAX team in Quebec, 15th in Canada and in the global top 50 according to the official RE/MAX ranking. Tell us about your project.